DSCR Loan FAQ for Denver Real Estate Investors
You’re building your rental portfolio in Denver Metro’s fast-moving market, where properties over $550,000 pull strong cash flow from tenants. But traditional banks fixate on your personal W2 or tax returns, ignoring the property’s real earning power. We see this every day with local investors snapping up multi-family units in Aurora, Littleton, and beyond—you need financing that matches the numbers, not your day job.
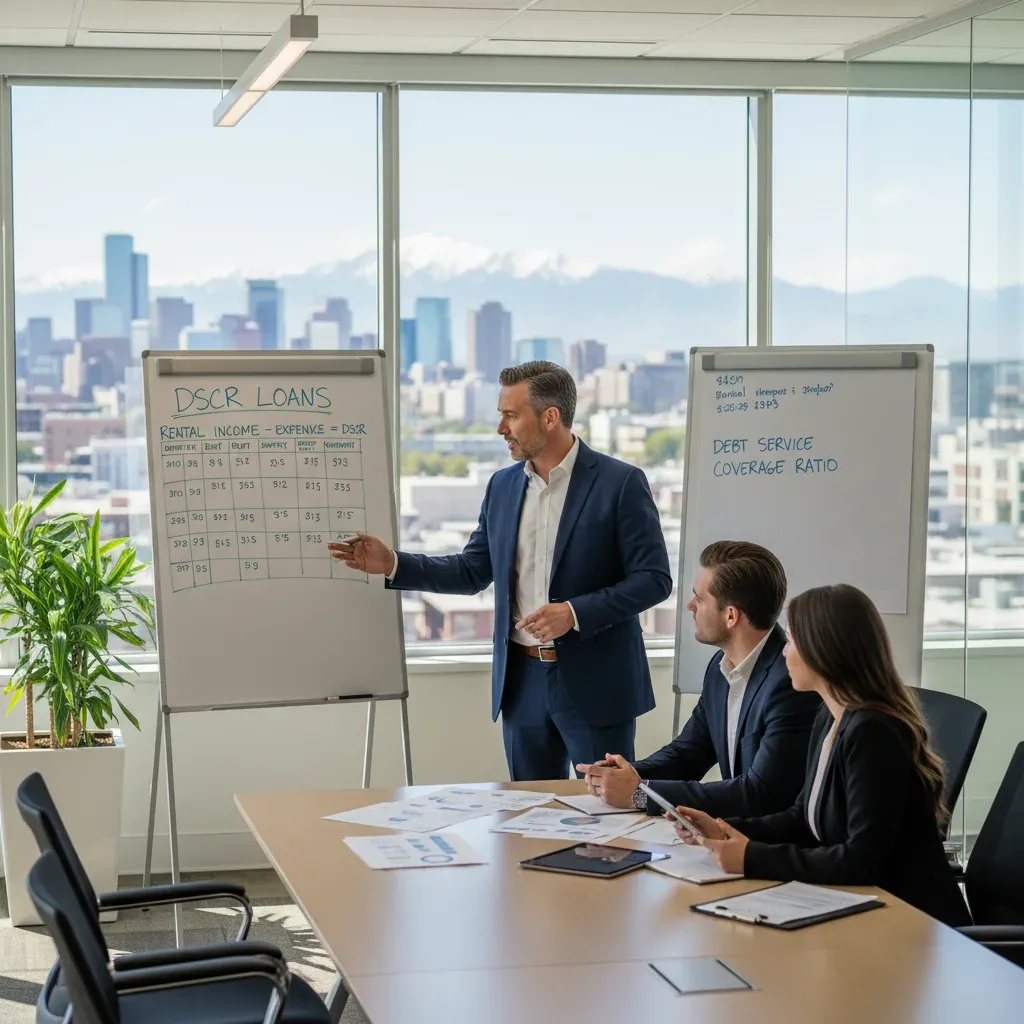
That’s DSCR loans: we qualify you using the rental property’s net operating income (NOI) divided by the mortgage payment, typically targeting a 1.0-1.25 ratio. Judy Shultheiss (NMLS #2449910) and our team at Forward and Reverse Mortgage answer these top questions from Denver investors daily. Not all borrowers qualify—terms apply.
Here are the straight answers:
DSCR Loan Process Questions from Denver Investors
How do we qualify you for a DSCR loan without personal income docs?
We base approval on the property’s net operating income (NOI) divided by the full mortgage payment—principal, interest, taxes, insurance, and HOA (PITIA)—aiming for a 1.0-1.25 ratio per investor lender standards like those from Visio Lending. Strong Denver Metro rents, say $3,000/month on a $550k duplex minus 25% reserves for vacancy and capex, yield NOI that covers payments easily. This skips your W2 or tax returns because the property proves itself, letting you scale portfolios faster without personal DTI limits.
What documents do we need to start your DSCR loan application?
Send us current lease agreements, the past 12 months’ rent statements or bank deposits verifying collections, and an appraisal ordered to Fannie Mae guidelines for accurate ARV. Property insurance quotes and HOA statements follow. We pull comps from Aurora and Littleton markets because local data drives the LTV cap at 75-80%, ensuring the loan fits cash flow realities—your docs confirm tenants pay on time, which locks in approval.
How long does DSCR loan closing take in Denver?
Our process runs 30-45 days from full docs because underwriters verify NOI stability first via third-party rent rolls, then clear title at Arapahoe County standards. Day-one app to pre-approval takes 48 hours since we upload directly to lenders, which means you bid on that Littleton fourplex without delays—faster than banks chasing your 1099s.
What’s the down payment on a DSCR loan for investors?
Expect 20-25% down on investment properties because lenders require 75-80% LTV to buffer cap rates around Denver’s 6-7%. Multi-family units drop to 20% since stabilized NOI hits ratios quicker, freeing your cash for rehab—which positions you to refi out later at stronger equity.
You see your properties generate real cash flow. You know traditional loans ignore that strength. You deserve DSCR financing that matches Denver’s investor edge. That’s why local pros call us first.
DSCR Loan Cost, Pricing, and Value Questions from Denver Investors
What do DSCR loan interest rates look like right now?
DSCR loan rates run 0.75-1.75% higher than conventional mortgages because lenders price for investment risk, yet Denver’s strong rents make them pay off fast—a $600k Aurora fourplex at 7.25-8.25% carries $4,200 monthly PITIA, covered easily by $5,500 gross rents at 1.25 DSCR. That extra spread means you build equity in cash-flowing assets without personal income hurdles, scaling your portfolio twice as quick. Rates fluctuate with markets—Judy Shultheiss (NMLS #2449910) pulls your exact quote from our investor lenders. Not all borrowers qualify. Terms apply.
What fees come with a DSCR loan in Denver?
Origination hits 1-2% of loan amount, plus appraisal at $650-900 for multi-family comps in Littleton or Aurora, and underwriting $1,200-1,800 to verify NOI stability. Total upfront fees equal 2.5-4%, which translates to $12K-24K on a $500k loan—but that unlocks 75-80% LTV on properties banks reject, recovering costs in months via tenant payments. We shop five lenders for the best terms, keeping junk fees out.
How much are DSCR loan closing costs for investors?
Denver closings total $8K-15K including title, escrow, and recording at Arapahoe County rates, plus lender-specific reserves. Choosing DSCR means those costs fuel a stabilized rental generating $1,500+ monthly NOI after expenses, directly offsetting the outlay while traditional loans stall your deals over W2s. Our team handles title directly from our Aurora office at 3000 S. Jamaica Court, Suite 280.
When does a DSCR loan deliver better value than conventional financing?
Higher pricing delivers when your rentals outperform—DSCR lets you close on five properties yearly versus two, compounding returns at Denver’s 6.5% cap rates. That 1% rate premium shrinks against portfolio growth worth $100K+ annually in equity. Get your free estimate today.
DSCR Loan Safety, Compliance, and Regulation Questions from Denver Investors
Do DSCR loans meet federal safety standards like Dodd-Frank?
DSCR loans fully comply with Dodd-Frank’s Ability-to-Repay (ATR) rules because we verify the property’s NOI covers PITIA at a 1.0+ ratio, proving the investment sustains itself without personal income risks. Notice how traditional banks overlook this—your Aurora duplex stands strong on its rents alone. Judy Shultheiss (NMLS #2449910) ensures every file hits these marks, shielding you from regulatory red flags that derail non-compliant deals.
How does DSCR lending handle RESPA and fair lending requirements?
We disclose all fees upfront per RESPA guidelines, listing origination, appraisal, and title costs clearly so you see the full picture before closing. Realize a hidden fee sneaks in on weaker lenders—ours stay transparent, audited to Colorado DORA standards at our Aurora office. That means your DSCR loan closes clean, with no surprises flagged in the final walkthrough.
What protects investors in DSCR loans from over-using?
Lenders cap LTV at 75-80% under Non-QM protocols, matching Denver’s 6-7% cap rates to prevent cash flow squeezes. Picture a fully loaded portfolio tipping over from loose terms—that’s the danger QM exemptions balance for investors, where property performance rules. Our underwriters stress-test NOI against vacancy scenarios, locking in stability.
Are there state-specific regulations for DSCR loans in Colorado?
Colorado DORA oversees us directly, requiring NMLS licensing like Judy’s #2449910 and annual audits for investor programs. We report every DSCR loan to maintain compliance, which keeps your multi-family in Littleton protected from shifts in lending rules. Not all borrowers qualify. Terms apply.
You recognize regulations safeguard your growth. You see compliant loans scale portfolios safely. You deserve DSCR financing built on solid standards.
Secure Your DSCR Loan and Scale in Denver Metro
Denver properties deliver strong NOI that traditional loans overlook. DSCR financing matches that power directly to approval. Local investors scale portfolios faster this way.
Once pre-approved, you bid on Aurora duplexes without delays. Picture closing that Littleton multi-family next month, cash flowing from day one. Our crews handle it all from 3000 S. Jamaica Court, Suite 280, Aurora—Judy Shultheiss (NMLS #2449910) pulls your free quote today at 303-881-5514. Not all borrowers qualify. Terms apply.